Can Tho (VNA) – Prime Minister Pham Minh Chinh and the delegation of National Assembly (NA) deputies of Can Tho city on July 13 held a meeting with local voters, including lecturers, researchers, civil servants and staff from universities, colleges and scientific institutions across the city.

This marked the third voter meeting of the city’s delegation of NA deputies following the 9th session of the 15th NA, and notably, the first thematic session focusing on science and technology.

It was also the PM’s first voter engagement in Can Tho since the administrative merger of former Can Tho city with Hau Giang and Soc Trang provinces.

The meeting drew over 1,000 participants, including academics, postgraduate students, civil servants, and technology professionals. Delegates briefed constituents on the outcomes of the 9th NA session, which concluded after 35 days of rigorous discussion. The session saw the adoption of 34 laws, 14 legal resolutions and reviews of six draft bills. Significantly, the legislature passed a resolution amending several articles of the 2013 Constitution.

The NA also approved shortening the current legislative term and local council tenures (2021–2026) and confirmed that the general election for the next term will take place on Sunday, March 15, 2026.

Currently, the Can Tho NA deputy delegation has 21 members, including PM Chinh and NA Chairman Tran Thanh Man.
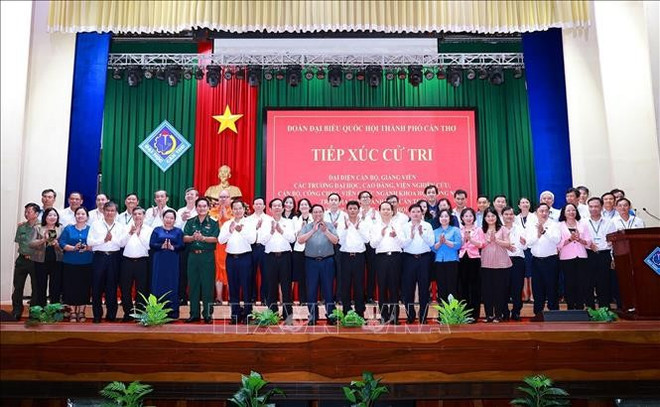
uuidf632a1a0-6f1c-40e1-9b35-b912dc865912code001library1type1mode1loctruecaptrue.jpg
Prime Minister Pham Minh Chinh and delegates at the meeting (Photo: VNA)

The delegation reported on local implementation of national policies related to science, technology, innovation, and digital transformation, particularly the rollout of Resolution 57-NQ/TW of the Politburo dated December 22, 2024.

At the meeting, voters raised various concerns, including issues related to scientific funding, commercialisation of research, digital skills development, and the need to retain talent within the national science and technology ecosystem. The PM and senior officials responded to these concerns, outlining measures to remove financial bottlenecks, reform research grant mechanisms, and boost private and social sector participation in innovation.

PM Chinh underscored the importance of increasing science and technology spending, from 3% of the state budget this year to 5% next year, along with tax incentives, preferential credit, visa facilitation, and housing policies for overseas Vietnamese experts.

He noted that priority will be given to developing high-quality human resources for emerging sectors such as semiconductors and AI, protecting intellectual property, and creating favourable conditions for collaboration between the “four pillars” of scientific research – government, academia, business, and the public.

The PM highlighted recent national achievements, including sustained political stability, social security, and economic growth. Vietnam’s GDP is projected to top ASEAN and rank among the world’s fastest-growing economies.

The Government’s push to eliminate substandard housing, particularly for policy-beneficiary households, is also expected to reach its targets ahead of schedule.

He also pointed to the smooth operations of the new two-tier local government model.

Praising Can Tho’s growing contributions to national development, the Government leader called for the city to lead in all key areas, particularly in science, technology, innovation, and digital transformation.

He urged the city to revive the stalled Can Tho Oncology Hospital project, accelerate the 1-million-hectare high-quality, low-emission rice programme for the Mekong Delta, and support digital education initiatives like “Digital Literacy for All”.

He encouraged Can Tho University to form digital transformation support teams to assist local communities and take the lead in human capital development for the semiconductor industry and the digital economy./.

VNA

To enhance the legal framework for business and foster sustainable development, on 17 June 2025, the National Assembly passed the Law amending and supplementing certain articles of the Law on Enterprises (“2025 Amended Law on Enterprises”), effective from 1 July 2025. Notable updates include:

Allowing public employees in scientific organizations to contribute capital and manage enterprises

Previously, the 2020 Law on Enterprises prohibited officials, public servants, and public employees from establishing, contributing capital to, or managing enterprises. To support the commercialization of scientific research under Resolution 193/2025/QH15, the amended law now permits public employees of scientific organizations to contribute capital and participate in the management of enterprises established by those organizations, provided they obtain approval from the head of the respective organization.

Stricter conditions for bond issuance by non-public joint stock companies

Unlike public joint stock companies, which are already subject to strict bond issuance rules under the Law on Securities, non-public joint stock companies faced looser regulation, raising risks for the market and investors. The amended law now requires that, for non-public joint stock companies, total liabilities (including the proposed bonds) must not exceed five times their owner’s equity, based on the latest audited annual financial statements. This limit does not apply to state-owned enterprises or bonds issued for real estate projects.

Introducing regulations on beneficial owners of enterprises

Following the FATF’s 2023 recommendation to enhance financial transparency and strengthen anti-money laundering measures, the amended law introduces the concept of a beneficial owner—an individual who ultimately owns or controls an enterprise, excluding state representatives in state-owned or state-invested entities.

Enterprises are now required to collect, update, and keep records of their beneficial owners at their headquarters or another designated location, and to provide such information upon request by competent authorities.

For enterprises established before 1 July 2025, beneficial owner information must be supplemented when amending business registration or notifying changes, unless voluntarily provided earlier. In practice, detailed procedures for notifying and updating this information are still pending government guidance.

The 2025 Amended Law on Enterprises addresses practical obstacles in corporate governance, supports innovation and growth, and demonstrates Vietnam’s commitment to anti-money laundering and international transparency standards.


Since 1 July 2025, Vietnam has officially operated under a new structure of provincial-level administrative units, following Resolution No. 202/2025/QH15 on the restructuring of provincial-level administrative units and the implementation of a two-tier local government model (provincial level and grassroots level).

According to Resolution 202, Vietnam now comprises 34 provincial-level administrative units, including 28 provinces and 6 centrally governed cities. Of these, 19 provinces and 4 cities were formed through mergers and consolidations, while the remaining 11 provinces and cities remained unchanged.

This restructuring has several important implications for enterprises, particularly concerning administrative procedures and boundaries.

Changes to registered addresses. The adjustment of administrative boundaries directly affects the registered addresses stated in enterprises’ legal documents, such as the Enterprise Registration Certificate, Investment Registration Certificate, company seals, signage, invoices, and product labels. As clarified by the Ministry of Finance in Official Letter No. 4370/BTC-DNTN dated 5 April 2025, enterprises are not required to immediately update their registered address solely because of the State’s boundary changes, and previously issued certificates remain valid. Enterprises may update their address at a convenient time or in conjunction with other business registration changes. However, it is advisable that enterprises proactively update their address soon to ensure consistency across all business documents, seals, and materials, thereby minimizing confusion and avoiding operational disruptions.

Changes in administrative procedure contact points. With the new administrative structure, many provincial-level government agencies such as the Departments of Industry and Trade, Construction, Finance, Agriculture and Environment, and Home Affairs have been reorganized to reflect the new boundaries. As a result, enterprises may now need to interact with newly designated agencies, which may involve changes in contact points, practices, and processing timelines. In this early phase, local authorities are still finalizing their internal arrangements and managing an increased workload, which may lead to delays in administrative procedures.

Recommendations for enterprises. Although the newly formed provincial and city governments officially commenced operations on 1 July 2025, detailed surveys and final demarcations of boundaries in some areas are still underway. This transitional period may pose challenges for enterprises seeking to update their records in line with the new boundaries. Enterprises are encouraged to carefully review how the new administrative map affects their operations, monitor official updates from local authorities, and prepare plans to adjust legal documents, signage, seals, invoices, and product labels to ensure compliance and smooth business operations.

In response to the significant negative impacts of U.S. tariff measures, global conflicts, and political instability on the Vietnamese economy, the National Assembly passed Resolution No. 204/2025/QH15 on 17 June 2025, extending support for businesses through a reduction of value-added tax (“VAT”).

Specifically, the National Assembly approved a 2% reduction in the VAT rate, applicable from 1 July 2025 through 31 December 2026. Unlike previous resolutions that applied the reduction in six-month intervals, this resolution provides for an 18-month reduction period, allowing businesses greater certainty in planning and implementing long-term strategies.

Notably, Resolution No. 204/2025/QH15 also expands the scope of goods and services eligible for the reduced VAT rate of 8%. Starting 1 July 2025, additional categories such as gasoline, coke, information technology products and services, and chemical products will benefit from the lower VAT rate, compared to earlier VAT reduction policies.

At present, the detailed implementation guidelines are still pending, as the Government is expected to issue a Decree to ensure consistent application of the policy. Nonetheless, the Decree is anticipated to adhere to the spirit and objectives of supporting businesses as articulated in Resolution No. 204/2025/QH15.

On 14 June 2025, the National Assembly of Vietnam officially passed the amended Law on Corporate Income Tax 2025 (“Law on CIT 2025”), demonstrating the State’s strong commitment to enhancing support for the private sector, particularly small and medium-sized enterprises (“SMEs”), and promoting the conversion of household businesses into enterprises. This is one of the key measures to implement Resolution 68-NQ/TW, reaffirming the private sector as a significant driver of the national economy.

Under the current legal framework, a uniform 20% corporate income tax (CIT) rate is applied to all enterprises, regardless of size or revenue. This, to some extent, has not encouraged the growth of SMEs, as the tax burden does not align with the financial capacity of this type of enterprise. To promote SME development, the Law on CIT 2025 introduces two preferential tax rates: a 15% tax rate applicable to enterprises with total annual revenue not exceeding VND 3 billion, and a 17% tax rate applicable to enterprises with total annual revenue exceeding VND 3 billion but not exceeding VND 50 billion. However, to prevent large enterprises from establishing SME subsidiaries solely to take advantage of these preferential tax rates, the law stipulates that such rates will not apply to subsidiaries or affiliated enterprises if the remaining enterprises within the affiliated group do not simultaneously meet the revenue criteria mentioned above. The implementation of preferential tax rates for SMEs is expected to provide significant financial support to the private sector, enabling SMEs to retain more capital for reinvestment and business expansion.

To facilitate the operations of small enterprises and reduce their compliance burdens concerning accounting and tax obligations, the Law on CIT 2025 also introduces a simplified tax calculation method based on a percentage of revenue. Accordingly, enterprises with total annual revenue not exceeding VND 3 billion are permitted to choose the method of declaring and paying CIT based on a fixed percentage of their revenue. The applicable rates vary depending on business activities: 0.3% for the distribution and supply of goods; 1.2% for manufacturing, transportation, services associated with goods, and construction activities where the contractor supplies materials; 1.5% for services and construction activities where the contractor does not supply materials; 4% for property leasing, insurance agency, lottery agency, and multi-level marketing agency activities; and 0.5% for other activities. This policy is anticipated to reduce compliance burdens and accounting costs while aligning with the small scale and limited management capacity of these enterprises.

Another notable point of the Law on CIT 2025 is the corporate income tax exemption for enterprises formed through the conversion of household businesses, aiming to encourage household businesses to convert into enterprises in line with the Government’s policies. Specifically, enterprises established through the conversion of household businesses, with total annual revenue not exceeding VND 50 billion, will be exempt from CIT for two consecutive years starting from the first year they generate taxable income. To ensure this tax exemption policy is applied to the appropriate beneficiaries, the law requires that household businesses must have operated continuously for at least 12 months before converting into an enterprise. Additionally, this exemption will not apply if the newly converted enterprise has its legal representative, largest capital-contributing member, or general partner simultaneously holding one of these positions in another operating enterprise or in another enterprise that was dissolved within 12 months prior to the registration date for the conversion.

Overall, the Law on CIT 2025 brings groundbreaking reforms, marking a significant step in improving the business environment, enhancing competitiveness, and promoting sustainable development for the private sector in Vietnam. The new policies will provide substantial support to SMEs, particularly household businesses transitioning into formal enterprises, thereby expanding the formal economy and contributing to long-term economic growth.

E-Invoices, Social Insurance, and New Rules Every Household Business Must Know

Starting from mid-2025 and especially from 2026, household businesses in Vietnam will face a series of major regulatory changes in tax and social insurance obligations. These reforms mark the end of the long-standing fixed tax method and the beginning of a more transparent, declaration-based system aligned with actual revenue. To ensure compliance and avoid penalties, household businesses must understand and prepare for these changes in a timely manner.

Mandatory e-invoices and electronic cash registers from 1 June 2025

From 1 June 2025, household businesses with annual revenue of at least VND 1 billion, operating in sectors such as food and beverage, hotels, supermarkets, retail, passenger transport, and personal services, must use e-invoices generated by electronic cash registers directly connected to the tax authority’s system. They will also be required to declare taxes monthly or quarterly, maintain simplified accounting books, issue e-invoices in compliance with Decree 123/2020/ND-CP, and self-calculate and pay VAT, personal income tax (PIT), and business license fees where applicable. This reform replaces subjective fixed-tax assessments with a fairer, more transparent system based on actual revenue.

Abolition of the fixed tax method from 1 January 2026

Effective 1 January 2026, the fixed tax method will be abolished under Resolution 198/2025/QH15 and Decree 70/2025/ND-CP. All household businesses must comply with general tax management requirements, including tax registration, declaration, payment, invoicing, and periodic reporting as prescribed by law.

Higher VAT and PIT exemption threshold from 1 January 2026

Under the new Law on VAT 2024, the threshold for VAT and PIT exemption will double from VND 100 million to VND 200 million per year. Although businesses earning no more than VND 200 million annually will be exempt from VAT and PIT, they remain obligated to register, declare, maintain accounting books, and issue e-invoices in accordance with the Law on Tax Administration 2019.

Mandatory social insurance for owners from 1 July 2025

For the first time, household business owners directly involved in regular business activities will be required to participate in mandatory social insurance, alongside their employees (if any). This requirement, effective 1 July 2025 under the Law on Social Insurance 2024, underscores the State’s intent to extend social security coverage to all economically active individuals.

Key compliance actions to prepare

To adapt to this new regulatory environment, household businesses should promptly review and update their tax registration details with local tax authorities, including adjustments to their registered business codes if actual operations differ. They must also ensure they have the proper equipment and software for issuing compliant e-invoices connected to the tax authority’s system. Even under the simplified accounting regime, they must maintain complete records of revenues and expenses to support tax declarations and facilitate inspections. Businesses should declare taxes accurately and on time, avoiding underreporting or delays, which could incur penalties.

For household businesses with large, stable operations and regular employment, it may be worth considering a transition to a formal enterprise structure under the Law on Enterprises. This change could offer additional benefits, including improved access to credit, stronger legal protections, and clearer obligations.

In summary, from mid-2025 — and particularly from 2026 — household businesses must be ready to move away from the outdated fixed tax method toward a modern, transparent tax and social insurance regime. Adopting e-invoicing systems, maintaining proper records, fulfilling declaration and reporting obligations, and planning for social insurance contributions are all critical steps to ensure smooth and compliant operations during this transition.

The Tax Sub-Department of Region XVI has issued Official Letter 7629/CCTKV. XVI-QLDN  dated 14/5/2025 to provide guidance to enterprises on resolving certain issues related to invoice issuance in cases involving the sale of shopping vouchers.

According to current regulations, invoices for the sale of goods must be issued at the time ownership or usage rights are transferred, regardless of whether payment has been received. However, shopping vouchers are not considered goods or assets. Therefore, when an enterprise sells shopping vouchers to customers, it is only required to issue a receipt for the amount collected and is not required to issue a VAT invoice at the time of voucher sale. Instead, a VAT invoice is only issued when the customer uses the shopping voucher to exchange for goods, based on the time when the ownership or the right to use the goods is transferred to the customer.

On May 6, 2025, the Customs Department issued Official Letter No. 4072/CHQ-NVTHQ providing guidance for enteprises on the handling of value-added tax (VAT) for cases where imported goods are damaged due to fire or storms.

Accordingly, the Customs Department confirmed that imported goods are subject to import duty and VAT, unless specific exemptions are provided by law. For import duty, the applicable laws clearly provide that importers may be entitled to a reduction of import duty in cases where goods are damaged while under customs supervision, with the reduction proportionate to the actual loss incurred.

However, regarding VAT, the current legal instruments governing VAT do not provide any provisions for exemption or reduction in the event that goods are damaged or destroyed. Therefore, the Customs Department confirmed that enterprises have no legal grounds to seek a VAT exemption or reduction for imported goods that have suffered damage.

As part of efforts to implement the revised 2024 Law on Value-Added Tax, the Ministry of Finance is developing a Draft Decree (“Draft”) that aims to clarify and operationalize new VAT regulations. The Draft is expected to improve tax transparency, strengthen administrative oversight, and assist businesses in achieving compliance. Key proposals under the Draft include several significant adjustments.

One notable change is the proposed reduction in the threshold for non-cash payments required to qualify for input VAT deductions. Currently, a non-cash payment is required for purchases of VND 20 million or more. The Draft lowers this threshold to VND 5 million (including VAT), reflecting a stricter approach to discourage tax fraud and enhance traceability in transactions.

The Draft also introduces clearer definitions for goods and services not subject to VAT. For instance, preliminary processed agricultural products are now defined as items that have undergone basic processes such as milling, peeling, drying, canning, or preservation using inert gases or sulfur. This clarification aims to help taxpayers and authorities more clearly identify qualifying VAT-exempt agricultural goods. Additionally, the Draft proposes extending VAT exemption to include artificial products that replace human body parts, as well as imported goods classified as relics, antiques, and national treasures in accordance with legal provisions. These clarifications are expected to facilitate more consistent interpretation and application of VAT exemptions.

Regarding VAT for promotion, under current regulations, promotional goods and services provided free of charge have a taxable price of zero. However, ambiguity remains for cases involving price reductions during promotions. To address this, the Draft specifies that the VAT taxable price in such instances shall be the discounted price applied during the registered or notified promotional period under commercial law.

To support businesses involved in supplying goods and services taxed at the 5% VAT rate, the Draft introduces new provisions for VAT refunds. Enterprises exclusively conducting 5% VAT activities may claim a refund if accumulated uncredited input VAT reaches VND 300 million or more over a 12-month period. Businesses with mixed VAT activities (5% and other rates) may also qualify for refunds if they can account separately for input VAT related to their 5% VAT-rated activities, and the threshold of VND 300 million is met.

In general, the Draft aims to provide clearer guidance and more consistent enforcement of the new VAT Law. The proposed amendments balance the objectives of effective tax administration with the need to simplify procedures and support business operations. If adopted, these changes are expected to facilitate smoother implementation of the VAT law and reduce interpretive uncertainties for both taxpayers and tax authorities. 


On May 16, 2025, the Ministry of Health promulgated Circular No. 12/2025/TT-BYT (“Circular 12”), governing the registration for marketing authorization (MA) of pharmaceutical products and active pharmaceutical ingredients (APIs) in Vietnam. Circular 12 officially supersedes Circular No. 08/2022/TT-BYT, Circular No. 16/2023/TT-BYT, and Circular No. 55/2024/TT-BYT. 

Compared to the previous regulations, Circular 12 has simplified administrative procedures and provided greater clarity on specific regulatory requirements regarding registration dossiers and processes for MA. Key revisions introduced under Circular 12 are as follow:

Changes in documentation requirements and administrative procedures for MA registration

One key revision of Circular 12 compared to Circular No. 08/2022/TT-BYT, is the revised CPP requirement, as Circular 12 now allow submission of a single CPP from either the country of manufacture or an EMA/SRA country where the product is actually marketed, which enhances access to new drugs, vaccines and biologics. However, enterprise responsibilities are significantly reinforced. Specifically, the period for CPP authenticity verification is now extended to 03 years from the date of a regulatory sanction decision. Manufacturers and applicants bear full legal responsibility for the accuracy and legitimacy of their registration dossiers.

Regarding the MA renewal process, dossiers may now be submitted at any time prior to expiration date without a maximum time limit, enabling continuous market presence for strategic products. The new regulation also specifies that the product name may be changed during renewal. All other changes must be handled through corresponding variation dossiers. If a name change is approved upon MA renewal, this modification must be implemented no later than 12 months following approval.

Notably, to improve dossier quality, Circular 12 imposes stricter limits on dossier supplementation: a maximum of 02 rounds, each within 06 months, for initial registration, renewal, and variation. A third round is only permitted under exceptional circumstances, either at the request of evaluating experts (with Advisory Council approval) or from the Advisory Council itself. This emphasizes the need for careful preparation to ensure that the initial dossier is complete and consistent, with post-approval changes (if any) to be handled through appropriate variation or supplementation procedures.

Harmonization with international standards via reference assessment procedures and clinical data 

Circular 12 have provide new regulation on reference assessment procedures, applied to drugs granted MA by EMA/SRA authorities, provided the Assessment Report is submitted within 05 years of the initial approval date. The Drug Administration of Vietnam (DAV) will verify technical document consistency with the reference dossier, and independently assess administrative and technical documents that differ. Assessment Reports from the EMA/SRA must be the official, final version, accompanied by any relevant decisions (if applicable), and must detail the evaluation of product quality, safety, and efficacy, along with the legal basis and scientific rationale for approval. At a minimum, these reports must cover administrative contents, quality, safety and efficacy data, together with a comparative equivalence table following Form 09/TT.

Clinical dossier requirements under Circular 12 also differ significantly from earlier regulations. Circular 12 mandates clinical data demonstrating safety and efficacy, sets clear exemption criteria for clinical trials or specific trial phases, and specifies cases requiring Phase IV trials. Circular 12 also outlines detailed clinical documentation requirements for new chemical drugs, vaccines, biologics, new non-innovator drugs (including first generics and super generics), and traditional or herbal medicinal products.

Delineation in authority to grant MA and shorten approval timelines 

Circular 12 modifies the MA issue authority. Accordingly, the DAV will issue MAs following consultation with the Advisory Council for the following cases: newly authorized drugs within the 03 years; withdrawn products (voluntarily or by order); critical variations (e.g., ETC/OTC reclassification, changes to indications, dosage, administration route, and patient population); and the designation of innovator drugs, reference biological products, or submissions involving bioequivalence (BE) studies. Circular 12 then empowered the DAV to grant MAs directly, without Advisory Council consultation for products: that have held MA for 05 years; non-critical variation dossiers; and updates to the package insert to align with approved innovator drugs.

To ensure timely access to medicines and minimize MA approval delays, Circular 12 shortens dossier evaluation timelines: 12 months for new registrations; 9 months for new registrations via the reference pathway; 3 months for major variations and minor variations requiring prior approval; and just 20 working days for minor variations requiring notification only. For contract-manufactured (CM) or technology-transferred (TT) drugs, evaluation timelines are also encouraged to be shortened: no more than 3 months for drug products prior to contract manufacturing and drug products prior to technology transfer already granted an MA, and no more than 9 months for those without an existing MA. 

Circular 12 contains several entirely novel provisions implemented for the first time, necessitating additional guidance from the DAV to ensure uniform application across the pharmaceutical sector. For enterprises, the new regulations under Circular 12 promise to simplify both the dossier requirements for obtaining MA as well as reducing the processing time. Therefore, proactively understanding and adapting to these significant changes in Circular 12 will be a key factor in maintaining a competitive advantage in the market. Circular 12 will take effect from July 1, 2025.
